Roof Insurance Claims in Los Angeles, CA
Roof insurance claim help in Los Angeles from a roofer means inspection, photographs, a written repair estimate, and being on site when the adjuster visits. The claim itself stays with you. Only the policyholder or a licensed public adjuster negotiates with the insurer.
- ★ 4.9 on Google · 69 reviews
- Same-day or next-day bookings
- Based in Van Nuys, CA
On this page
- Roof insurance claim help in Los Angeles: what a roofer can and cannot do
- When should you start a roof insurance claim in California?
- How to document roof damage for a claim
- Meeting the insurance adjuster on your roof
- What if a roof claim is denied, short or needs a supplement?
- Which claim deadlines and paperwork should you watch?
- Insurance roof replacement in Los Angeles: coverage, deadlines and contracts
- What affects the cost of a roof repair on an insurance claim?
- Why Clear Shield for roof insurance claim documentation in Los Angeles
- Common questions
Roof insurance claim help in Los Angeles begins with a clear line between two jobs. Your insurer decides what the policy pays. We deal with the roof: what happened to it, how much of it needs work and what that work costs. This page sits within our emergency roof repair work and explains where we fit into a claim.
Roof insurance claim help in Los Angeles: what a roofer can and cannot do
Most confusion comes from mixing up the roofer's job and the claim itself. Here is the split.
| Task | Who does it |
|---|---|
| Inspect the roof and attic | Clear Shield |
| Photograph and measure the damage | Clear Shield |
| Write a repair estimate | Clear Shield |
| Be on site when the adjuster visits | Clear Shield, if you ask |
| Report the claim and read the policy | You |
| Discuss amounts and terms with the insurer | You, or a licensed public adjuster |
| Accept, dispute or appeal the decision | You, or a licensed public adjuster |
Only the policyholder or a licensed public adjuster negotiates. California treats negotiating a claim for a fee as public adjuster work, and you can check a license at insurance.ca.gov. Clear Shield is a roofing company and does not act as one.
When should you start a roof insurance claim in California?
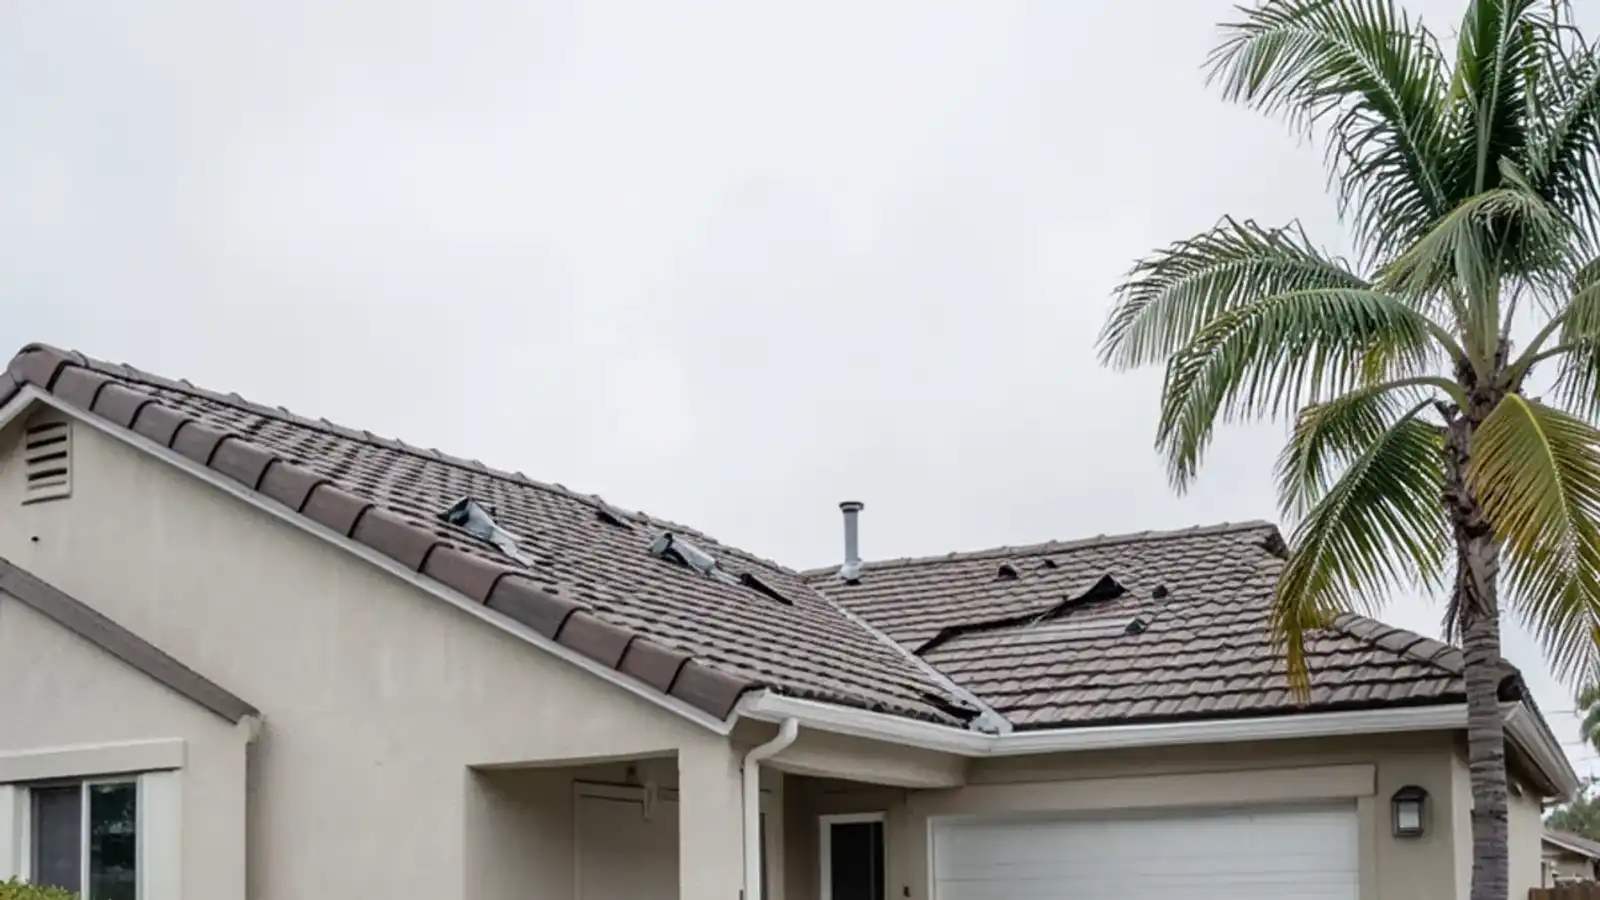
Start when you see storm, wind, tree or fire damage, not when a stain appears weeks later. Policies generally respond to sudden damage, while wear and age usually are not covered, so the date and cause matter. Read your policy for the filing time limits it sets.
In practice the order looks like this:
- Make it safe. Stay off the roof and protect the opening if you can reach it from the ground or call for tarping.
- Photograph everything. Do this before anything is moved or covered.
- Report the claim. Tell your insurer what happened and ask what they need.
- Get a written repair estimate. We inspect, document and price the roof in writing.
- Meet the adjuster. We are on site if you ask, and the insurer decides coverage.
- Read the decision before signing the repair contract. Check what is covered and what is not.
How to document roof damage for a claim
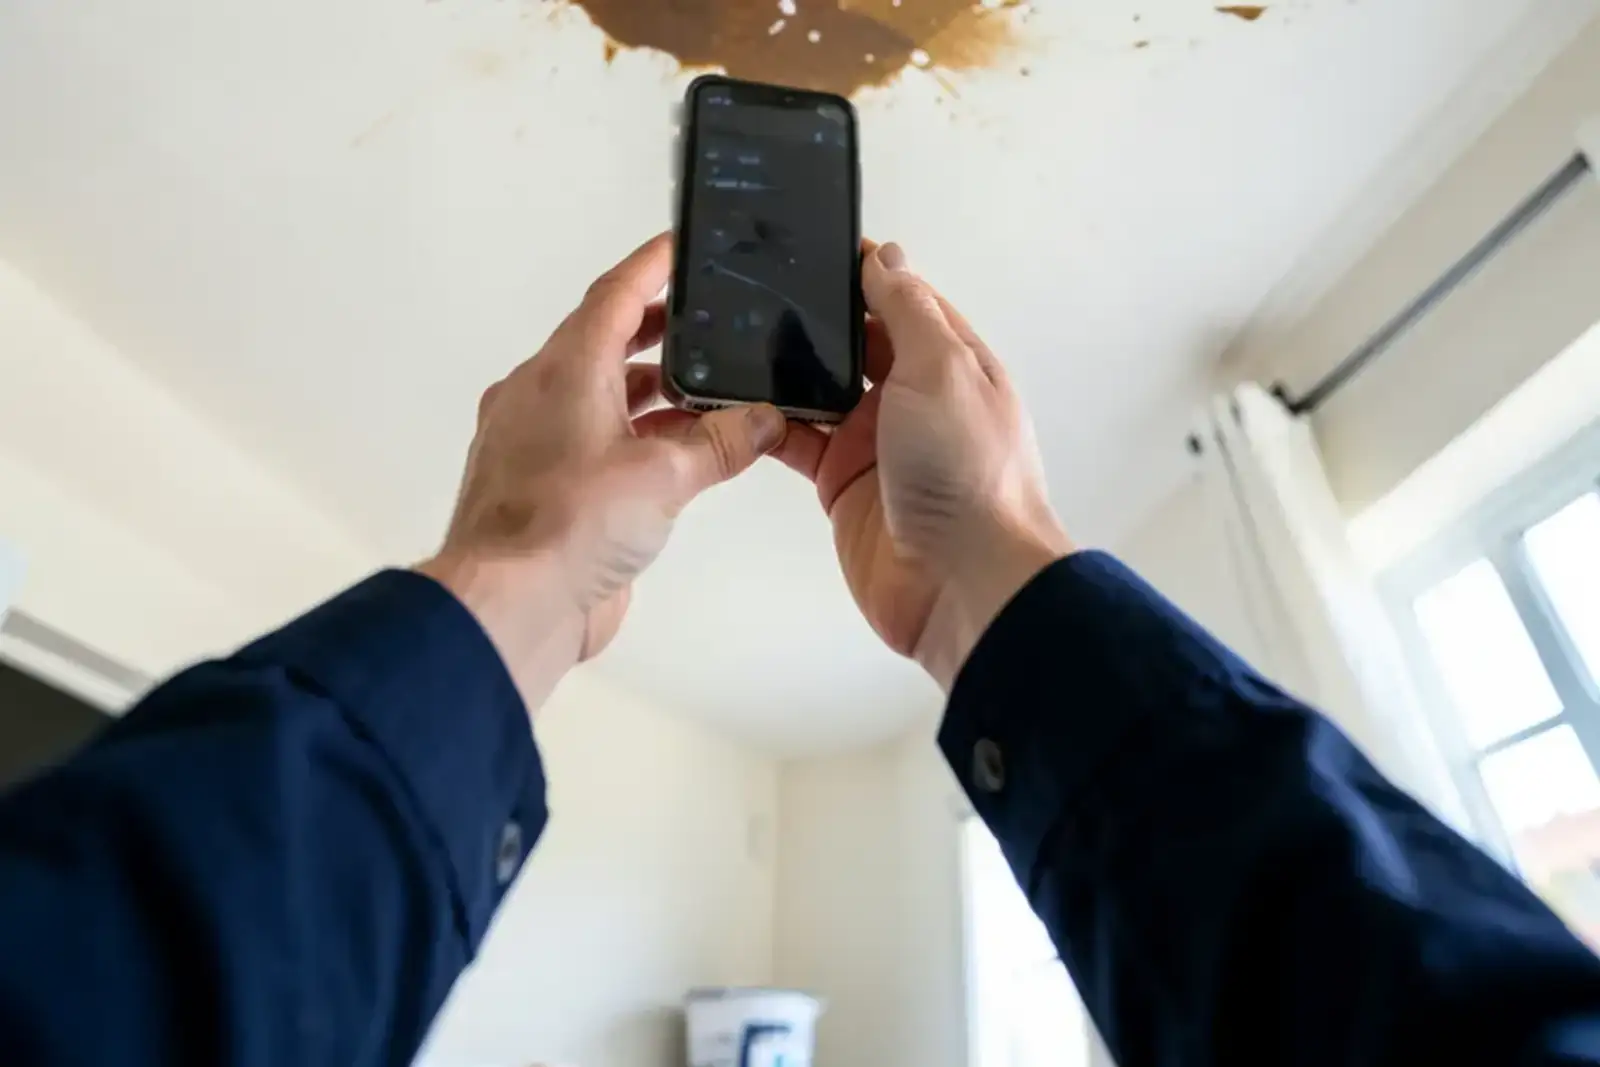
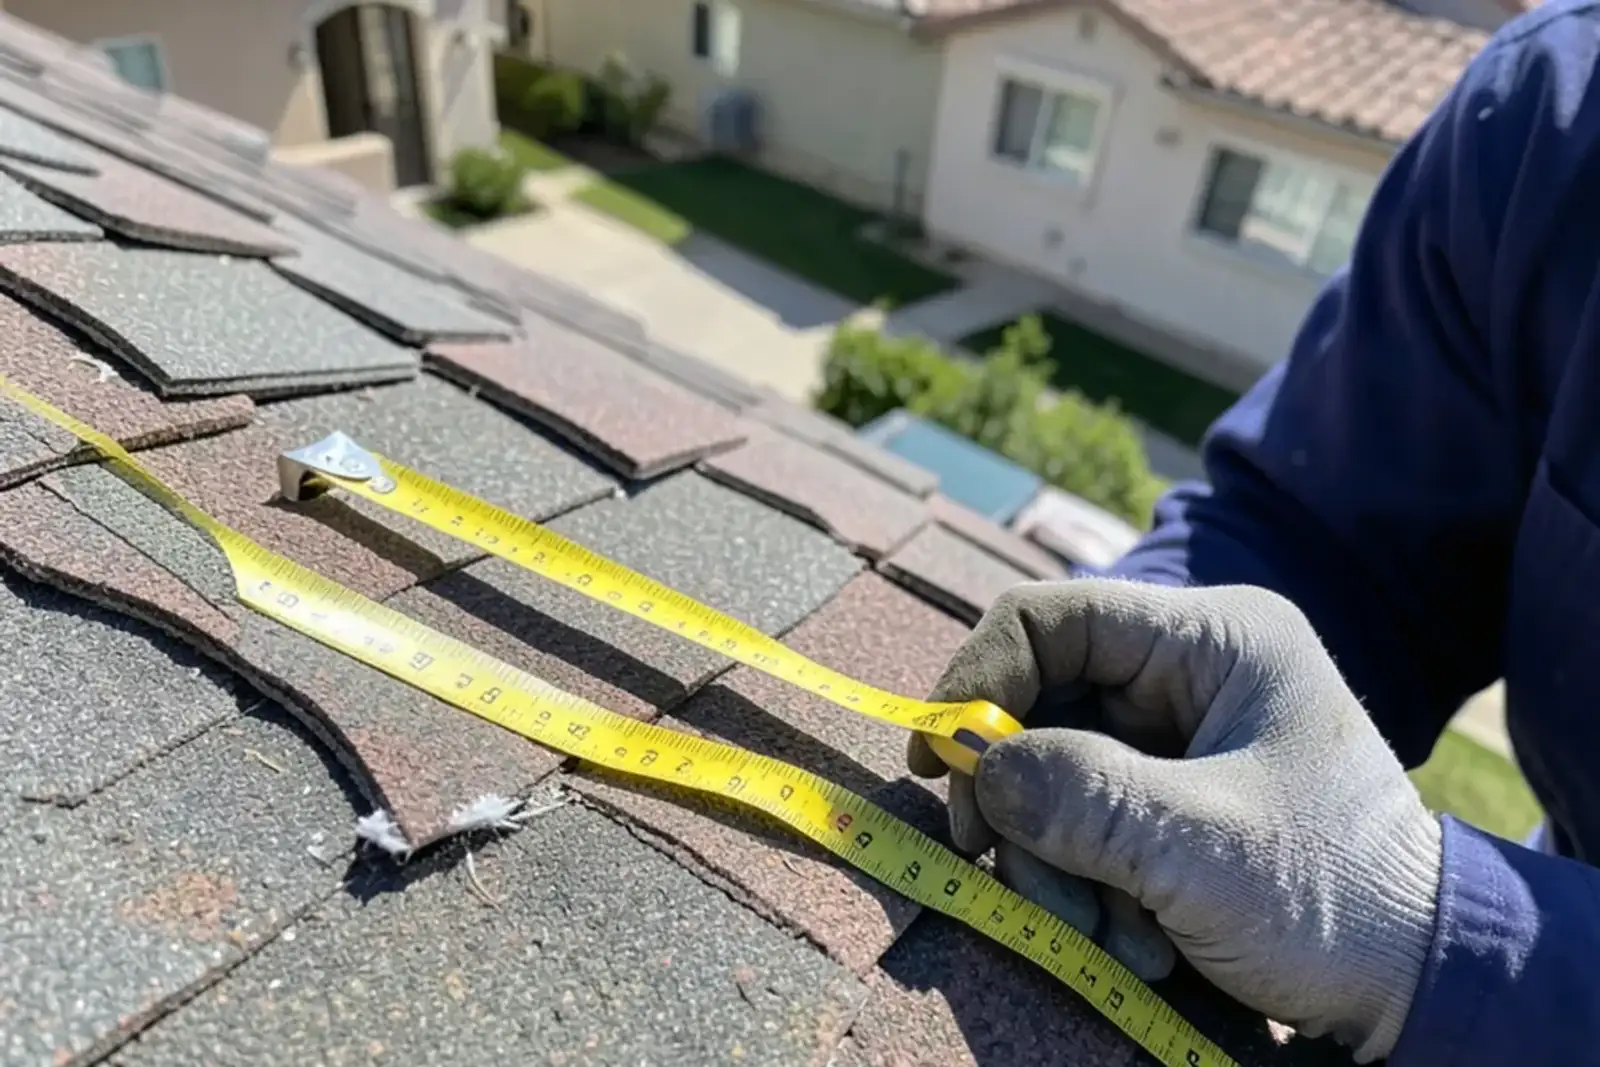
Good records make the claim easier to read, whoever reads it. Take wide photos of each slope, then close shots of each damaged spot with a tape or coin for scale. Photograph the ceiling stains, attic, gutters and any debris. Note the date and weather.
We add what a homeowner cannot easily get: measurements, a walk of the slopes and attic, and a written scope of repairs with photos. One reviewer in Van Nuys describes a roof inspection and damage documentation for an insurance claim. Another mentions pictures and measurements before quoting, and a third says drone photos came during the work.
Meeting the insurance adjuster on your roof
The adjuster works for the insurer and decides how much of the roof the policy will pay for. A roof visit is usually short. Having your own record of damage in hand means nothing gets lost.
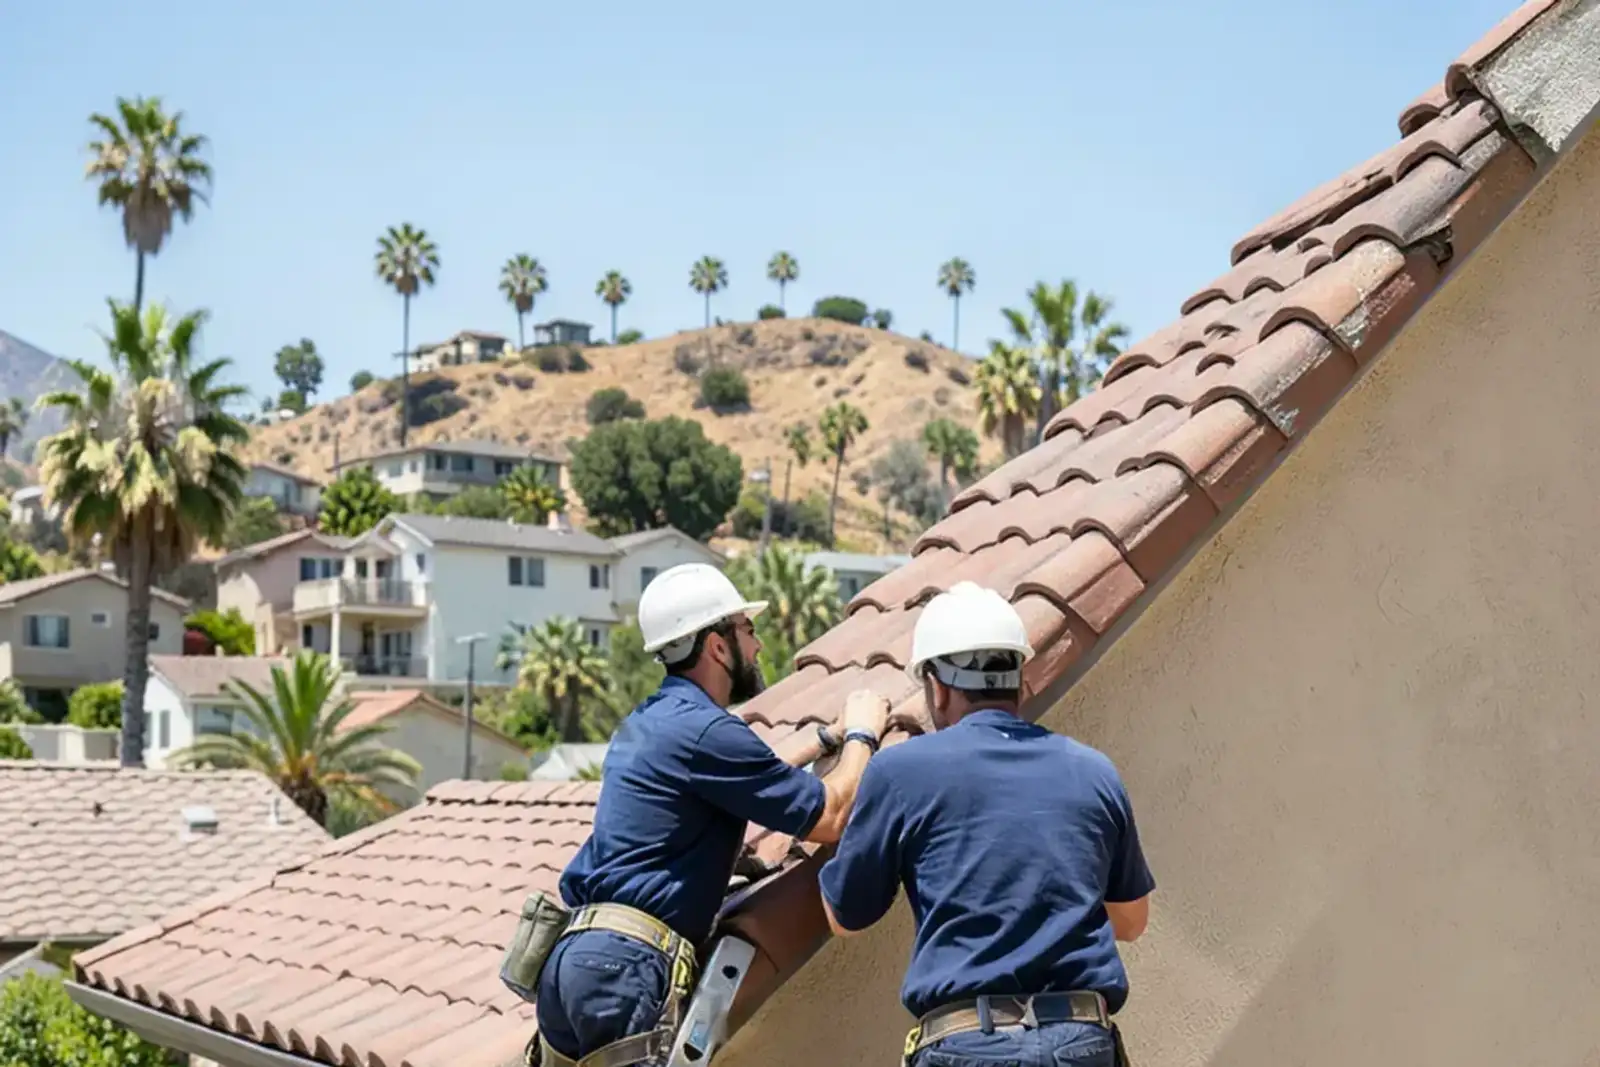
If you ask, we can be on site when the adjuster visits. We walk the slopes with them, show the damage we photographed and answer questions about the roof. We do not speak for you. Ask the adjuster to put the scope and any exclusions in writing. Our guide to meeting the insurance adjuster on your roof lists what to ask.
What if a roof claim is denied, short or needs a supplement?
A denial is not always the end. Ask for the decision in writing, with the policy language behind it. Compare it with your photos, then send anything new, such as an inspection report or repair estimate, and ask for a review. If you disagree, the California Department of Insurance takes consumer calls at 800-927-4357. A licensed public adjuster may negotiate for a fee.
A supplement is different. It is a request for more money when the work turns out bigger than the first scope, such as soft decking found under old roofing. Photograph the problem before it is covered and tell the insurer promptly. For a longer read, see our guide to appealing a denied roof insurance claim in California.
Which claim deadlines and paperwork should you watch?
Your policy sets the clock, so read the clause that limits when you can act against the insurer. Write down the storm date and the day you first saw damage. Keep every letter from the insurer. For a deadline question, ask the Department of Insurance or an insurance attorney.
Insurance roof replacement in Los Angeles: coverage, deadlines and contracts
Whether the policy pays for a repair or a full replacement is the insurer's decision. For a longer read, see whether insurance covers roof replacement in California. Insurers consider roof age and condition, and a FAIR Plan policy is a basic fire policy to which wind can be added, so ask what yours includes.
California's claims regulations generally require an insurer to acknowledge a claim within 15 days and to accept or deny it within 40 days after proof of claim. If you have a problem, the Department of Insurance can help.
For the contract itself, the down payment is limited to $1,000 or 10 percent of the price, whichever is less. You generally have at least three business days to cancel, and longer for seniors and disaster repairs. If the claim leads to a replacement, a permit is generally needed. The contract should say who pulls it. Never agree to waive or absorb your deductible.
What affects the cost of a roof repair on an insurance claim?
The insurer pays what the policy allows, less your deductible. The roofer's price is a separate number, and the two may differ. Price depends on roof size and pitch, the material, how much decking is damaged, and whether the work reaches replacement and its permit. As a market reference, Angi estimates a roof replacement in Los Angeles at roughly $4 to $12 per square foot, averaging about $8.60, or about $17,200 for a typical 1,700 square foot home (accessed November 2026).
Written pricing follows our look at the roof. If the insurer's figure and ours differ, the written scope shows why. If water is coming in while the claim is open, see our emergency roof tarping and emergency roof leak repair pages.
Why Clear Shield for roof insurance claim documentation in Los Angeles
We keep to the roof side of the claim, and that is a deliberate boundary. We inspect, photograph, measure, write the repair estimate and meet the adjuster if you ask. Reviewers in Van Nuys mention pictures and measurements before quoting and a visit the same night for a leak.
What Van Nuys customers say about inspections and storm repairs
“They also performed a full water test afterward to make sure the leak was fully resolved, and everything stayed dry.”
“The crew’s workmanship looked top-notch, and they kept me updated by sending drone photos of the roof work as it happened, which was really helpful since I wasn’t about to climb up there myself!”
“During the new roof installation, a small leak showed up after some seasonal rain, and Frederick and the crew responded right away, even on a Sunday morning, to fix it fast.”
4.9 on Google · 69 reviews as of November 2026. Read all reviews
We cover Santa Monica, Calabasas, Marina del Rey and Santa Clarita. Salt air along the coast, such as in Santa Monica, wears metal flashing, which is worth noting when you document wear versus storm damage.
Roof Insurance Claims: common questions
Can you meet the insurance adjuster at my home?
Yes, if you ask us to and the schedule allows. We can be on site when the adjuster visits, walk the roof with them, and point out what we documented. You stay the person talking to the insurer, and the decision on the claim is between you and them. Tell us the visit date as soon as you have it so we can plan around it.
What can I do if my roof claim was denied?
Ask the insurer for the decision in writing with the policy language it relied on, then compare it with your photos. You can send new documentation and ask for a review. The California Department of Insurance consumer line is 800-927-4357. A licensed public adjuster may negotiate for a fee, and you can verify one at insurance.ca.gov. We can supply an inspection report and repair estimate.
Will a claim raise my premium?
It depends on your insurer, your policy and the kind of claim, and we cannot say how yours will treat it. Ask your insurer or agent before you file, and ask how an inquiry differs from a filed claim. Insurers also consider roof age and condition when writing or renewing coverage, so ask what yours requires.
Can a roofer negotiate with my insurer for me?
No. Negotiating a claim for a fee is reserved for the policyholder and for a licensed public adjuster, whom you can verify at insurance.ca.gov. A roofer can inspect, photograph the damage, write a repair estimate and be on site when the adjuster visits. Talking terms, amounts and settlement with the insurer is not part of that work.
How should I photograph roof damage for a Los Angeles insurance claim?
Take wide photos of each slope and close shots of every damaged spot, with a tape measure or a coin beside it for scale. Photograph ceiling stains, the attic and gutters, and note the date and the storm. Do it before anything is moved or tarped. From a ladder only if it is safe. We can add measurements and drone photos.
What is a supplement on a roof insurance claim in California?
A supplement is a request for added payment when the work turns out larger than the first estimate, such as rotted decking found once old roofing is removed. Photograph the problem before it is covered, then send the insurer the photos and a revised estimate. We can write that up for you; the request goes from you to the insurer.
Should I sign a roofing contract before the adjuster visits my Los Angeles home?
Protect the roof first, but hold off on a full repair contract until the insurer has seen the damage. California limits a home-improvement down payment to $1,000 or 10 percent of the contract, whichever is less, and generally gives at least three business days to cancel. Read any contract carefully before you sign, and keep receipts for emergency protection.
Areas served for roof insurance claims
- Downey, CAA large stock of 1950s ranch homes, so roof age comes up with the insurer and dated photos of the existing roof help the file.
- Fullerton, CAHistoric Spanish-style homes with clay tile, so documentation should show tile type and underlayment, since matching affects scope.
- Walnut, CAMany tile-roofed tracts, where a storm claim often involves slipped or cracked tile and the adjuster needs to see the underlayment.
- Gardena, CA1940s-60s homes beside light-industrial buildings, so roofs of very different ages and types may come up in one visit.
- La Habra Heights, CAHillside lots with long driveways make roof access tricky, so the adjuster walk-through leans on safe ladder and drone views.
- Rancho Cucamonga, CALarge 1980s-2000s tract roofs now need underlayment work, and an insurer will want proof of sudden damage versus wear.
- Bell, CASmall-lot homes mix with light-industrial roofs, so documentation separates storm damage from ordinary wear on older flat sections.
- East Rancho Dominguez, CADense postwar homes in an unincorporated community, where any permit tied to a claim-driven repair goes through LA County.
- Marina del Rey, CASalt-laden harbor air corrodes metal roof parts on condos and apartments, which matters when separating wear from storm damage.
- Santa Monica, CA
- Calabasas, CA
- Santa Clarita, CA
- Ventura County, CA
- Channel Islands Beach, CA
- Riverside, CA
- Irvine, CA
- Fontana, CA
- Ontario, CA
- Rancho Cucamonga, CA
Need roof insurance claims?
Call and tell us what you are seeing on the roof. We will take it from there.